Hrefna Sigfinnsdóttir, CEO, Creditinfo Iceland
Hrefna Sigfinnsdottir discusses 35 years in financial services, the evolution of credit data, and why AI will move from experimentation into the core of finance.
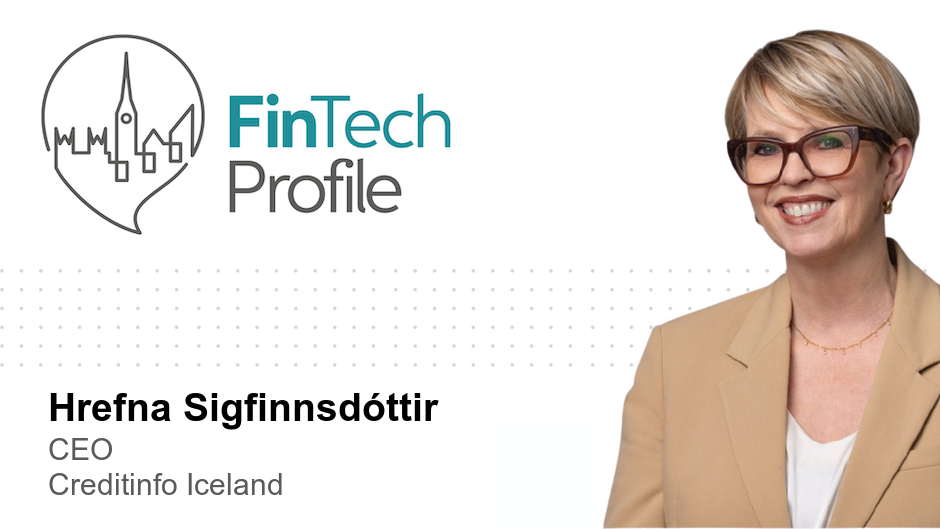
Today we're delighted to speak with Hrefna Sigfinnsdóttir, CEO of Creditinfo Iceland at Creditinfo. With 35 years in financial services spanning capital markets, investment management, and now credit information, Hrefna brings a unique perspective on how data and AI are transforming risk management and financial decision-making across the Nordic region and beyond.
My questions are in bold - over to you Hrefna:
Who are you and what's your background?
I have spent roughly 35 years working in financial services, so in many ways I have grown up alongside the development of Iceland's modern financial sector.
I started my career in capital markets and had the opportunity to work at the Central Bank of Iceland, Skandia and Nasdaq Iceland before moving into investment management. I was a fund manager for a private equity fund and later spent 11 years at Landsbankinn as a Managing Director, leading the asset management and capital markets divisions. In 2021, I joined Creditinfo as CEO of Creditinfo Iceland and I've not looked back since!
What is your job title and what are your general responsibilities?
I am the CEO of Creditinfo Iceland and serve on the management board of Creditinfo Group. I set the direction for the business and make sure we execute it commercially, technologically and culturally. I also ensure we turn data into actionable insights while maintaining the highest standards of privacy, security and governance. We're part of a global group but remain deeply connected to our customers and the Icelandic market.
Can you give us an overview of your business?
Creditinfo helps organisations make better decisions using data. Creditinfo was founded in Iceland as Lánstraust in 1997 and has since developed into an international credit information and data services group operating in more than 40 countries.
In Iceland, our business covers much more than traditional credit reports. We provide credit and business information, KYC and due diligence solutions, fraud prevention, sustainability data, decisioning tools and analytics services.
We help organisations answer critical questions about their customers, counterparties and risks, often automating decisions through data, analytics and monitoring tools.
One of our strengths is the combination of deep local data and market knowledge with the technology and experience of an international group. Creditinfo operates across a wide range of markets, which gives us exposure to developments in financial technology and data analytics around the world, while our Icelandic team understands the particular characteristics of the Icelandic market.
Tell us how you are funded?
Unlike many FinTechs, Creditinfo is a mature business with a long history. In 2021, a majority stake was acquired by Levine Leichtman Capital Partners, while the founder retained a minority holding. Today our focus is on long-term growth, technology investment and customer value rather than fundraising.
What's the origin story? Why did you start the company?
The original business, Lánstraust, was established in 1997 to improve access to credit-related information and transparency in the Icelandic market. The founders saw an opportunity to improve transparency and help organisations make more informed decisions about risk.
Who are your target customers? What's your revenue model?
Our customers include banks and other financial institutions, insurance companies, lenders, fintech companies, telecommunications companies, retailers, professional services firms and businesses that need to assess customers, suppliers or potential partners' credit risk.
We also work with organisations that need KYC, fraud prevention, business information, monitoring and data analytics solutions.
Our revenue model is primarily B2B, combining subscriptions, data access, reports, software and tailored solutions depending on the customer's requirements. We also have consumer subscription services in Iceland.
If you had a magic wand, what one thing would you change in the banking and/or FinTech sector?
I'd make it easier to share and use data responsibly across the financial ecosystem. Too often, valuable information sits in separate systems and formats. The challenge isn't having enough data, but using it effectively while maintaining strong privacy protections and governance. If we get that balance right, financial services can become both more efficient and more inclusive.
What is your message for the larger players in the Financial Services marketplace?
The largest financial institutions have enormous amounts of data and very sophisticated technology, but that doesn't necessarily mean they are making the best possible use of it either.
My message would be: think carefully about what decisions you are trying to improve, rather than simply asking what new technology you should buy.
AI, automation and data platforms are extremely helpful tools but the real question is how they improve the customer experience, reduce risk, increase efficiency or enable a better decision.
I would also encourage large institutions to collaborate more with the wider ecosystem. Banks don't need to build everything themselves. There is enormous expertise in fintech, data and specialist technology companies.
The institutions that succeed will, in my view, be the ones that combine their scale and customer relationships with the agility and innovation of the wider technology ecosystem.
Where do you get your Financial Services/FinTech industry news from?
I tend to use a combination of mainstream financial news, specialist FinTech publications and the research and commentary coming directly from financial institutions, regulators and technology companies.
For specialist fintech news, I regularly look at FinTech Insider / 11, Finextra and The Financial Times for the broader financial-services picture.
I also find LinkedIn surprisingly useful because some of the most interesting discussions around AI, financial infrastructure, regulation and data are now happening directly between industry practitioners rather than only through traditional publications. The only problem is finding the time to read all of the news!
Can you list 2 people you rate from the FinTech and/or Financial Services sector that we should be following on LinkedIn, and why?
Jesper Brodin is a Swedish business leader who was CEO and President of Ingka Group (the largest IKEA retailer) from 2017 until 2025, after a 30-year career with IKEA. He is now a Senior Advisor to the IKEA Foundation, Chair of the Earthshot Prize and Chair of the B Team, among other roles. He has also been involved with the UN Global Compact and World Resources Institute.
What makes him particularly interesting is his experience leading a huge traditional organisation through digital transformation. During his time at IKEA, he pushed the business toward an omnichannel model, digitalisation and greater use of technology.
Roelfien Kuijpers is a senior financial-services executive with DWS Group and is based in New York. Her background includes extensive experience in asset management and financial services, and she has also served on the Women's Leadership Board at Harvard Kennedy.
Roelfien has a very interesting perspective on financial services, investment and leadership, having held senior positions in the asset-management industry. I particularly enjoy following people who can look at the changes taking place in finance from a broader perspective, and Roelfien brings that combination of financial-services experience, international perspective and leadership to the conversation.
What FinTech services and/or apps do you personally use?
I use a mixture of traditional financial services and digital tools in my everyday life, and what I find interesting is that the distinction between "banking" and "FinTech" is becoming increasingly blurred.
What's the best new FinTech product or service you've seen recently?
One area that has particularly caught my attention is the emergence of AI-powered financial services - not simply chatbots, but systems that can understand financial information, automate parts of decision-making and give customers much more tailored insights.
Finally, let's talk predictions. What trends do you think are going to define the next few years in the FinTech sector?
I think there are five big trends. First, AI will move from experimentation into the core of financial services. The focus will shift from testing capabilities to delivering measurable value across areas such as underwriting, fraud prevention, customer service, compliance and financial analysis.
Second, data quality will become a key competitive advantage. AI is only as effective as the data behind it, making reliable, well-governed information more important than ever.
Third, financial decisioning will become increasingly automated. Processes such as lending, onboarding, KYC and risk assessment will become faster and more efficient, while governance and explainability remain critical.
Fourth, trust will become a differentiator. As AI plays a larger role in financial decision-making, transparency, privacy, cybersecurity and responsible use of data will become essential.
Finally, fintech and traditional financial services will continue to converge. The most significant innovations will come through collaboration between financial institutions, technology providers, data companies and regulators.
For Creditinfo, this presents a significant opportunity. Our focus has always been on helping organisations make smarter decisions using data. As technology evolves, the challenge will be turning information into actionable insight while maintaining trust. Those that achieve both will help create financial services that are faster, more efficient, and ultimately more valuable for customers.
Many thanks to Hrefna for taking the time to share her insights with FinTech Profile. You can learn more about Creditinfo on their website.